Sunday, February 25, 2007

Investing 101 - 401 K by Srikant

Disclaimers: Don’t consider any of this as certified legal or financial advice. We are not tax attorneys, financial advisors, or retirement planners. Consider this as one of the inputs in your planning process.

Discussion items

1. Company Match 401K.

Make sure you utilize all the company contribution. For example, if the company is matching contribution 100% for the first 1% and 50% for 5% of your contribution, choose your contribution to be 6% at the very least. If conditions favor, choose maximum contribution allowed by IRS, 15,500 for 2007. This will increase by $500 for the next few years as per a law passed in the congress.

2. Penalty.

Money that is withdrawn prior to 59 ½ typically incurs a 10% penalty tax unless a further exception applies. This penalty is of course on top of the "ordinary income" tax that has to be paid on such a withdrawal. The exceptions to the 10% penalty include: the employee's death, the employee's total and permanent disability, separation from service in or after the year the employee reached age 55, substantially equal periodic payments under section 72(t), a qualified domestic relations order, and for deductible medical expenses (exceeding the 7.5% floor. Further state and local income taxes also are applied.

3. Going back to India

See above section on penalty. See the attached email chain below (Source: http://groups.msn.com/R2INRIFinanceAndInvestments/general.msnw?action=get_message&ID_Message=30650). The link http://www.r2iclub.com/060210/r2i-finance-general.htm is a good link in general for anyone planning to go back to India and thinking about finances. The parent link is http://www.r2iclub.com/master.htm

Dear all,

My current employer offers a 401(k)plan with matching contribution & 100% vesting. Is it still wise to continue 401(k) contributions since I don't have long terms plans in the US?

Should I take advantage of the employer contribution now and later on pay taxes & penalty or better pay taxes and stay out?

I am on H1B & married.
Please advise.


It's a free lunch. Take it even if you R2I. Contribute the amount eligible for your employer matching. See below to understand how you get benifited :

Case I. You don't contribute to 401k :

Assuming that your employer matches 1:1 for your first $1000 of pay and you're in 30% tax bracket. If you don't contribute that $1000 to 401k, you pay a tax of $300.

So, money in your pocket = $700.

Case II. You contribute to 401k :

Your contribution = $1000

Employer's match = $ 1000

Total = $ 2000

Say, you want to R2I after one year and want to withdraw this money.

If you keep this money in a stable value fund with a return of 4%, the total amount in your 401k account grows to $ 2080 after one year. When you withdraw, you pay a penalty of 10%, i.e $ 208 (on $ 2080) and 30% tax, i.e $ 562.

Now, money in your pocket = 2080 - 208 - 562 = $ 1310.

Your gain by contributing to 401k = 1310 - 700 = $ 610

The above example assumes that you're not eligible for RNOR period in India. If you're eligible, you can plan withdrawal during RNOR period and may totally avoid or pay less taxes. Your gains will be higher in that case. See RRK's home page for more details.

See http://www.thehindubusinessline.com/bline/2003/03/11/stories/2003031102610800.htm for details on RNOR (Non-resident, Resident and Resident but Not Ordinarily Resident

4. How much %

See item 1 above. If the company does not provide any match at all, it is still a good way for retirement saving. Some companies do not provide any match but do provide a plan that is administered by a third party so that employees can invest.

5. Kind of investments.

There are different ways of doing investments. Depending on the age and risk appetite a mixture of mutual funds, bonds, company stock funds, etc is suggested. Let us talk in detail about these choices.

6. Balancing with Current expenditure.

Not sure what this is supposed to mean. Lets talk tomorrow

7. Loans on 401 K.

Recommend not doing it unless there is no other option available. See following snippet below from http://articles.moneycentral.msn.com/RetirementandWills/InvestForRetirement/7MostCommon401kBlunders.aspx

Taking out loans

What seems like a great idea -- Borrow your own money! Pay yourself interest! -- has plenty of traps for the unwary:

  • The biggest pitfall is the risk you take should you lose your job. Your loan would become due, and, if you couldn't pay it back at once, you would owe income taxes and penalties on the unpaid balance.
  • The interest rate you pay yourself may be lower than what you would pay most other creditors, but paying yourself interest is no substitute for the real return you would be earning if you had invested those payments instead.
  • Borrowing from your retirement funds is often a sign that you're overspending -- particularly if you're using the proceeds to pay off credit card debt. People who use "easy outs" like 401(k) and home equity loans to pay off their cards often don't change the underlying behavior that put them in the hole. They just run up their balances again -- winding up another day older and deeper in debt.

8. Is it really worth it?

It is for you to decide after we have the discussion

9. How can you convert to IRA ?

Need to do more research…have no clue.


10.


11. 401 Transfer.

By transfer, if you are referring to a rollover, it is typically allowed when you change employers. You have 3 options:

    1. Keep existing amounts at the old employer and start a new one at new employer
    2. Roll over old employer account to an IRA and start a new one at new employer
    3. Roll over old employer account to new employer account

WE can discuss pros and cons tomorrow.

12. Age Factors.

For discussion tomorrow. The earlier you start the better it is :>)


Additional Notes

Some Background information (Source: Wikipedia -http://en.wikipedia.org/wiki/401k)

The 401(k) plan is a type of employer-sponsored retirement plan in the United States and some other countries, named after a section of the U.S. Internal Revenue Code. A 401(k) plan allows a worker to save for retirement while deferring income taxes on the saved money and earnings until withdrawal. The employee elects to have a portion of his or her wage paid directly, or "deferred", into his or her 401(k) account. In participant-directed plans (the most common option), the employee can select from a number of investment options, usually an assortment of mutual funds that emphasize stocks, bonds, money market investments, or some mix of the above. Many companies' 401(k) plans also offer the option to purchase the company's stock. The employee can generally re-allocate money among these investment choices at any time. In the less common trustee-directed 401(k) plans, the employer appoints trustees who decide how the plan's assets will be invested .

All assets in 401(k) plans are tax deferred. Before the January 1, 2006 effective date of the designated Roth account provisions, all 401(k) contributions were on a pre-tax basis (i.e., no income tax is withheld on the income in the year it is contributed), and the contributions and growth on them are not taxed until the money is withdrawn. With the enactment of the Roth provisions, participants in 401(k) plans that have the proper amendments can allocate some or all of their contributions to a separate designated Roth account, commonly known as a Roth 401(k). Qualified distributions from a designated Roth account are tax free, while contributions to them are on an after tax basis (i.e., income tax is paid or withheld on the income in the year contributed). In addition to Roth and pre-tax contributions, some participants may have after-tax contributions in their 401(k) accounts. The after-tax contributions are treated as basis and may be withdrawn without tax. The growth on after-tax amounts not in a designated Roth account are taxed as ordinary income.

Articles of interest

7 common 401k blunders

http://articles.moneycentral.msn.com/RetirementandWills/InvestForRetirement/7MostCommon401kBlunders.aspx

7 ways to boost return

http://moneycentral.msn.com/content/P108575.asp

Also refer http://www.fidelity.com/, http://www.vanguard.com/ and browse around for good information about investing, 401k, returns on various stock funds, etc. You can also look at msn.com money section, money magazine and other financial magazines for useful tidbits.

Tuesday, February 06, 2007

Investing 101 - Introduction

We are planning to start a series of classes on investing for about 10 weeks, once a week, every sunday at 10:30 AM - 12:30 AM.

This Sunday, Feb 4th, my friends and I got together and chalked up a plan for the next 10 weeks or so.

These are the topics we are going to discuss, a few presenters have signed up, so look out for their names.
  1. 401 K - Srikant - Feb 18th, (We need one more person for this) for about 2 weeks.
    • Company Match 401K.
    • Penalty.
    • Going back to India
    • How much %
    • Kind of investments.
    • Balancing with Current expenditure.
    • Loans on 401 K.
    • Is it really worth it?
    • How can you convert to IRA ?
    • How can I invest 401 K money on my own?
    • 401 Transfer.
    • Age Factors.
  2. Roth IRA. (Pradnya) - 1 week
    • What is it?
    • How to pick the investment firm?
    • Can you do it on your own?
    • Tax benefits.

  3. Life Style (Ramya) - 1 week
    • Latte factor
    • Environment
    • Part Time work
    • Pregnancy, Kids
    • Health
    • Shopping, deals.
  4. Real Estate - Home buying (Bharath) - 1 week
  5. Bonds, Mutual Funds - 1 week (*)
  6. Stocks - 2 weeks (Kamal, upto 2 more people can talk here.)
    • What is it?
    • Technical terms
    • Large, Mid, Small caps.
    • etc.
  7. Investing in India (Sujan, Anyone else?) - 1 week
  8. Real estate investing - other than home - 1 week
  9. Misc 1 - 1 week. (*)
    • Savings
    • Cash in hand
    • Tranfers to India.
    • Employer benefits
    • HSA
    • Tax.
    • etc.
  10. Misc 2 - 1 week (*)
    • US Dollar
    • Liabilities, Assets
    • Business.
For everyone, who is going to join the class, please pick a topic you can are comfortable with presenting and let me know.

Looking forward to writing more Investing 101 posts as the weeks progress. Stay tuned !

Thursday, October 12, 2006

Digg this and you will help to save a 4 year old's life!

I know this is unusual, but this is a genuine. The parents of the kid are my friends friend.
All contributions are tax exempt and make payments to the Cancer Patients Aid Association. If you can't contribute atleast Digg it, so somebody else who sees it can contribute Every cent helps and every Digg increases the chance of saving this kids life

read more | digg story

Sunday, September 17, 2006

Go to the Movies !

For the last couple, maybe three weeks I have become crazy watching movies during the weekends. I just turn on the television and start watching the movie that is currently playing, usually its one of the cute ones with Steve Martin, Sanjay Dutt, Paresh Rawal or Lindsay Lohen.

Here goes my movie review for the movies that I have watched in the past few weeks.

  1. Chup Chupke - Paresh Rawal (Gundya) and Rajpal Yadav (Bandya) are very funny in this movie and what makes the movie amazing is Kareena Kapoor is mute.
  2. Lage Raho Munnabhai - A big hit, lot of hype, but I thought the movie was ok, I was set for a senseless comedy movie like Chup Chupke, and Sanjay Dutt and Gandhi-giri was kind of jarring, maybe he is becoming a changed man with age, future MP ? :)
  3. Kabhi Alvida na Kehna - The bachans are good, actually everyone else is good in the movie, the movie is kinda long, but its good. I know a lot of people out there are going to hate this movie, but Shahrukh has done a pretty good job.
  4. Citizen Kane - Supposed to be a revolutionary movie in it's time (1940's) but kinda boring in the 2000's.
  5. V for Vendetta - I watched in twice, once in the night, once the day after in the morning, I really liked this movie, beautiful oratory, had to pause and rewind a bunch of times to understand what V was saying. Must watch movie.
  6. Click - I liked this move, Adam Sandler was good and his gal, Kate Beckinsale, was a babe.
  7. Cheaper by the Dozen - watched this for the 2nd/3rd time, I like it.
  8. Father of the Bride 2 - Sugary movie :)
  9. Summer Catch - Baseball, teenage movie, sugar, it was good.
  10. Naalai - Gangster Tam movie, it was good, any movie without Vadivalu is good :) (ok now I am blabbering).
  11. Gangster - This is a very well made movie, its in the Dil Chahta He league.
  12. Maid in Manhattan - 2nd/3rd time .. Ramya loves it, ok ok, I like it too.
  13. Snakes on a Plane - This is an amazingly crappy movie, leave your mind out and have fun, some scences with snakes are just ridiculous, but it is watchable in it own crappy way.
  14. Why we Fight - it's a good movie.
  15. Thiruta Payle - It starts off well with an extra marital affair, but kinda gets predictable at the end, watchable once.
  16. What a girl wants - it's good, man these TV movies!
Some other movies that I can always watch are Vertical Limit and Parent Trap. O, how can I forget The Day of the Jackal?!

Ok, I forgot about all the bad movies I watched and I no longer remember movies like Kasturi Maan.

That is enough waste of time for now, I am going to swear off movies for a few months.

In the back of my mind, Honey, when is that harry potter movie coming?

Friday, April 21, 2006

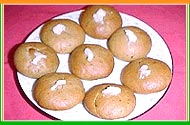
Dal Bati Recipe

I have decided to try something new, I am going to put up the recipe for Dal bati. Let me know if you actually make it at home. I will come over to try some, just kidding, maybe on your second or third attempt.

Ingredients For Bati

1. Wheat Flour - 2 cups
2. Sooji (Semolina)
3. Ghee/Clarified butter - 4/5 Table spoon
4. Salt
5. Water

Preperation for Bati
Proportion of Wheat flour to sooji is 3:1. Mix the wheat flour, sooji, salt and ghee to make the dough, the dough should be consistent, without lumps as in the case of chapati dough or paratha dough. Make round balls out of this dough, about size of your palm. This is called bati.

Insert the batis in water and boil for a few minutes, the top layer of the bati will become a bit white. Stop boiling at this time.

Pre-heat the oven at 450F. Put the batis inside the oven for 10 minutes. Turn them upside down and let them bake for another 10 minutes. The batis are done when they become brownish. The batis will have a hard outer shell. Break the outer shell a bit my pressing them in between your palms. The batis will be hot so you might need a piece of cloth to protect your hands.


Take a soup bowl and fill about half the bowl with ghee. So much for you watching your calories or your cholesterol. :) Immerse couple of batis in the the ghee and let them soak for at least 5 minutes.


Ingredients For Dal

1. Toor Dal / Lentil - 2 cups.
2. Tomato - 2
3. Onion - 1
4. Jaggery - 4 tablespoons
5. Olive Oil (Boy, we are getting healthy here!)
6. Mustard
7. Cumin Seeds - Jeera
8. Garlic Flakes.
9. Ginger.
10. Curry Leaves.
11. Green Chilli.
12. Red Chilli
13. Lemon - 1
14. Turmeric - 1/2 table spoon
15. Red Chilli powder - 2/3/4 table spoons - according to taste
16. Salt
17. Coriander Leaves.

Preperation For Dal

Pressure cook the toor dal in water for 10 minutes. Beat the pressure cooked Toor Dal to form a consistent paste (I do not like blobs of dal) and leave aside. Finely chop the onions and tomatoes.

Splutter the mustard and cumin seeds in oil, add all the spices (8 - 12 above) to the oil. Then fry the onions in healthy olive oil till golden brown, add the jaggery and tomatoes at this time. Add the red chilli powder and turmeric powder to this mixture. Add the toor dal and 1 -1 1/2 cups of water to the mixture. Add salt and let the dal boil for 5-10 minutes. Squeeze the lemon after the dal has boiled. Garnish with coriander leaves.

Side Dishes
  1. Chopped onions, with red chilli powder, salt and lemon.
  2. Shredded Mango, with red chilli powder.
  3. Heated oil with mustard, cumin seeds and lots of red chilli powder. This can be added on top of the dal to make it spicier.
  4. Green Chutney
  5. Tamarind - Date chutney
Any combination of the above side dishes can be used. Whatever you like.

Serving
  • Crush the ghee dripping bati to form small pieces. The bati will be soft on the inside. Only the outer shell is a bit hard.
  • Add more ghee to the bati, If you do not do this, just because you are are calorie conscious, your stomach is going to have some difficulty digesting. You have been warned!
  • Serve the side dishes.
  • Serve the Dal in a bowl.
  • Take some portion of the bati, add some dal on top of it. Mix the side dishes and enjoy!
The taste you are going for here is a combination of ghee, sweet and lemony. This dish is extremely filling and sleep inducing. Usually a guy can have 2 batis and a girl can have 1 to 1.5.

Drink lots of water! especially after your meal. The wheat needs it.

Joe Bless You!

George Carlin on Religion, an extermely funny article.

Here is the audio

Sunday, April 16, 2006

Thyagaraja Aradhana - Cleveland

This weekend RS and I went to the Thyagaraja Aradhana in Cleveland, OH. We were accompanied by two of our friends Satish and Sujan who are into Carnatic music. RS and I were looking for a relaxed weekend away from our to-do lists.

The aradhana is cleveland is a week long musical concert series showcasing works of the composer Thyagaraja.

On Saturday morning, the aradhana started with Pancharathna krithis, sung by professional and amateur musicians; these are the most famous work of Thyagaraja, I was so happy to recognize the first one :)

The highlight of Saturday was the carnatic music rendition by Padma Shri Sudha Ragunathan, she has a voice which is simply out of this world, the whole concert which lasted for about three and a half hours was just mesmerizing. We were also very lucky because we got the best seats in the house, 20 feet away from her on stage. I have never heard her sing before, but she had me hooked onto her voice from the very first song, how I wish she sang some ghazals :)


Posted by Picasa


On Sunday morning we attended a recital by the sisters Gayatri and Ranjani, they ended the recital to a standing ovation on the rendition of a Marathi abhang by Sant Gyaneshwar.

I have no clue when it comes to the Ragam, Tanam and Pallavi's of Carnatic music, but the trip to Cleveland was worth it.

Wednesday, February 08, 2006

Gods

No, I am not going to write about what I think of God. But, I am going to talk about the gods hanging on our walls. Everyone has a calendar to give you at the beginning of the new year which has the most beautiful of god pictures on them. So, you find it cute, get it home, put it on your desk, hang it on the wall.

After a year, when it has collected dust (ok maybe yours does not, mine does!) and has faded, what do you do about it?

Now, you really cant take it off the wall and throw it in the dustbin, after all its the god you have been praying to for the whole year (even if you did not remove the date leaf everyday) - My grandfather actually removed the leaf every day. Also, you need the space to hang the new calendar that has come in the new year and if you don't remove it and hang the new calendar elsewhere at the end of 10 years you will have a god wall :)) .. Or maybe god walls.

So, I usually take the picture off, give it to my mom, who in turn gives it to the temple. I am not sure what happens after that, maybe they send it to the "store" for recycling :) .. But the temple should really know what to do with all the gods, since it is really their business :)

What do you do with your gods ?

Thursday, January 26, 2006

Swami Playing the Violin

Here is swami playing the violin at 3 am. This was during our wedding reception weekend in the US. Swami ended the day with an excellent violin performance.


Link to the google video page

Tuesday, December 13, 2005

Whimsical Raconteur again on Sulekha :)

In the meantime she has had a short story published in DNA's ME magazine and another short story in India Abroad.

Sunday, December 11, 2005

Retirement Accounts - 401k's

I have been looking into getting free money, but then there is nothing that is free or maybe there is :) If your employer matches any amount of money that you put into your retirement account, then you maybe losing out on free money given away by your employer and some tax savings.

Example - Free Money
John Smith's employer matches 50% of the money John contributes to his 401K retirement account, upto 6% of John's salary. Also, this money comes out of John's salary pretax, so this reduces this current taxable income. Lets say John earns $2500 per month, he contributes 6% ($150) to his 401K savings account, his company matches 50%($75), so if John contributes $150 per month to his retirement account, his company puts in $75 (that is 50% instant profit). He does not earn any contribution from the company if he contributes nothing for his retirement. Some institutions give upto 200% of your contribution, $300 in John's case, for a total of $150.

Investments
This 401K money is put in various investments, depending on what you company provides, from a low yeilding money market account (better than most banks savings accounts) to mutual funds to stocks to self managed 401K's. There are ways in which you can get your favorite brokrage to maintain your 401K investments.

Tax Savings
John's initial taxable income was $2500 per month, @ 25% tax rate that is $625 in tax, now after his 6% contribution, his taxable income reduces to $2500 - $150 = $2350 and his tax reduces to $587.5, that is an additional $37.5 savings in taxes.

Taxes
If withdrawls from the 401K account are made after 59 1/2 years, then these withdrawals are taxed at the rate in which John falls in, at that age, this is expected to be less than his current rate of 25% because he might just be withdrawing $1500 from his 401k at that age.

Growing Money
It is said that money attracts money and the interest earned on compounding are great, if we take the average stock market return of 9% per year, $1000 invested by John at age 25 becomes $2367 at age 35, $5604 at age 45, $20413 at age 60. This is just the initial $1000, of course as John keeps adding more money per month in his retirement account, his final retirement nest egg is much bigger.

Cons

  • If John withdraws money before age 59 1/2 from his 401k he is subjected to penalty and taxes.
  • He has to pay taxes on the money in his retirement.

Personal Comments

  • I think it is good to maximize your 401 benefits, upto what your employer matches, so if your employer matches upto only 4% of your salary, keep your 401k contributions to 4%. Because the principal (your money and the matched money) and any income will be taxed in the future.
  • Roth IRA's: If the employer matches nothing, it is best to invest in Roth IRA's (more about this in the next post). Also, it is best to put your money in Roth IRA if you want to contribute more to your retirement account then what your employer matches. For eg. if John wants to put 10% of this salary in retirement accounts, he should contribute the first 6% in 401K and the next 4% in Roth IRA's

Links

Retirement Calulator - http://www.bloomberg.com/analysis/calculators/401k.html

More about Roth IRA's in the next post.

Tuesday, November 15, 2005

Satisfying Saturday !

Posted by Picasa

My Team was playing the UK-ISC Volleyball Tournament this Saturday. The medal and trophy say it all :) We won the final in 5 sets.

Tuesday, October 25, 2005

Monday, August 15, 2005

Asha for Education - Hats off to Medha

Medha told me recently that she is going to be running a 26.2 mile marathon.

O Man ! 26 miles, Indian girl ? Marathon? Running? (some of my stupid thoughts). So, I got more details from her:

Why?: To stay fit. To see if I can do it. To help children back in India.

Ain't that awesome?

Where?: Chicago, Oct 9th.

Training?: She started training at the beginning of this year. She has to train atleast three days a week. Also, the training gets tougher as the weeks go by. So if Medha runs 2 miles a day in week 1 she has to run 4 miles the next and 6 miles the week after that. There is a phase where the mileage reduces and goes back up again. Last weekend she ran 16 miles.

Too much hard work for me :)

Medha is running for Asha For Education, this group runs various projects around the country to provide basic education.

Medha's owns words and other details.

What can we do?: As a part of the run, medha is expected to collect donations to the tune of $2600+ . Various people and companies are sponsoring the runners and the event. So if you are interested in sponsoring Medha's run or seeing Medha's running log and to help Asha for Education please use this link

Happy Independence Day Posted by Picasa

Friday, August 12, 2005

मन* से रावण* जो निकाले* राम उसके मन मे है.

Not sure, if the Hindi is correct :), I picked this line up from the swades song pal pal hai bhari

* = corrected.

Monday, July 11, 2005

Harry Potter and the Half-Blood Prince

Pre-ordered from Joseph Beth !

Harry Potter and the Half-Blood Prince Posted by Picasa

I am second in line to read the book :(

Tuesday, June 28, 2005

Money – Investing.

The most important driving factor of our lives, still no one talks about it, people will talk philosophy, religion, emotions, books etc, Money zilch :)… I know nothing about that beast, except that I need to have it somehow and I need lots :)

I have been recently pursuing Investing, not that I have a lot of money to invest, but in general of how people make money and how money attracts money :) here are the few investing options that are out there:

  1. Get out of debt: This is the first evil, All Debt is bad, but some are better than the others, Credit card, personal debt, cars are among the worst. Anything you pay interest on is bad. Loan on your home is not as bad, but it needs to get off soon.

  2. Banks: For all those who just use the interest provided by the bank to grow your money, the days of 6-10% interest rate was for our previous generation not ours, the best we can do as of now is open an ING account whose current interest rate is 3%, which is better than most fixed deposits, If you need a recommendation to this let me know, in that way both of us can make money :)

  3. Real estate: If you are in the US (in most areas) and have a stable job (going to last 2 years or more) and have 5% or so down payment then buy a house and remember the mantra, Location! Location! Location! My personal opinion is not to overextend your self on the house loan, get a loan which you pay off in 10-12 years and own the house. Things like number of earning members of the family are important and things like wife’s future maternity leave should be carefully considered before you set down a price on the house you can afford.

    Other real-estate investments can be additional rental property purchase. This way the rental property pays for the loan and the property hopefully will appreciate in a few years :)

  4. Mutual Funds:
    Advantages

    • There are 9 categories of mutual funds, based on the risk level you are willing to take
    • There are more mutual funds then stock! I was surprised at this first but it is counter intuitive.
    • Since a mutual fund consists of a number of stocks, owning a mutual fund gives instant diversification.
    • Mutual funds should be No Load

    Disadvantages

    • You can loose money, Loss is possible with a mutual fund. It is not like a savings account :)
    • All funds have fees, which mean they will take a percent of the profit that is made by the fund. This is usually taken yearly and is in the range of 0.5% to 2%. I don’t like no fees, but they are necessary.
    • Profits are not huge (like doubling your money). The average mutual fund will give you like 10-20% in a good year.
    • Good mutual funds have a minimum ($2500) that you need to invest. Sometimes I think, I am not ready to risk 10% loss on $2500 of my hard earned money :)

    Difficulties

    • Finding a good mutual company.
    • Understanding Morning star ratings.
    • What should be the risk level?

  5. Stocks
    This is risky business:).You should own stocks, but do yourself a favor and don’t put all your money into it.
    Advantages

    • Profits can be great if you pick the right stock at the right time.

    Disadvantages

    • You are responsible for diversifying your own stocks. It is not very helpful if you put all your money into 1 company.
    • Fees, Scottrade Interactive Brokers probably offers the lowest fees amongst the online traders. At $7 for Market orders, this is pretty good; I have not found anyone reputed and cheaper then them. Though I don’t have an account here:)

    Difficulties

    • Needs a constant following of the market.
    • What stocks to buy?
    • When to buy?
    • When to sell?

  6. DRIPS
    Dividend Re-investment plans; these plans allow you to buy stocks of a company monthly. E.g. you can say I want to buy Home Depot $250 of home depot stock monthly or fortnightly.
    Advantages

    Disadvantages

    • There are fees associated with each purchase, like $2.50 each time to purchase stock of $250, which is 1% of your principal. So the stock has to appreciate at least 1% before you can realize any gains.


Any more Investing Ideas?

Friday, June 17, 2005

Birthday Treasure Hunt + Chakarapongal

If you thought getting gifts on a Birthday was easy, think again.


On my 28th (read 16th) Birthday, I had to go on a treasure hunt to get my gifts. This treasure hunt was prepared by RS and Prad. Also, its not 1 clue per gift, I have to solve 2 clues per gift.

  1. I have to solve the first clue to tell me what the gift is. (like baseball/cricket bats, ipods etc ;) )
  2. The second clue leads me to the location of the gift (basement, pile of clothes, cupboards etc.)
I have very little time to solve these clues, because the party audience is waiting and all the pressure is on me. I did manage to solve some on my own and others with lots of prompting :)


Here are the clues if you want to take a shot.

I will update this place with answers and pictures in a couple of days.


Questions 1a, I have to guess my first gift using this question.
Posted by Hello

Answer to 1a - Start Higlighting here => The last line gives it away easily, Its all part of the "game". We've played a lot of board games before so, the clue says "we have done this before and it is loads of fun". So the gift as a board game called "Balderdash". It was awesome :)


Question 1b, This is where my first gift is located.
Posted by Hello
Answer to 1b - Start Higlighting here =>
"The Smelly cat" phrase indicates a sock, shoes, pig sty, trash can something nasty. Since I take it on a walk once a week, it most probably is something like a trash can, "the lid", confirms that :). The unscrambled word is "PRADNYA", she finds it amusing that I am @ home with filth :) . So, the board game was behind the "trash can"


Question 2a, I have to guess my second gift using this question.
Posted by Hello
Answer to 2a - Start Higlighting here =>
This is a bit complicated :), lets start with the signs first, The exclamation mark is "NOT", the second sign is a directional sign with "SOUTH" highlighted. The third sign is mountains, trees and the base is highlighted for "LAND". Which results in "Not South land Alley", this is a bowling alley that we frequent. The next sign is for "GOLF", !G but R means ROLF :) . The clue "Will your friday question change" means, I usually ask if we can go bowling each friday, so the gift is something that will distract me from asking this question :) ... which means its probably a game of some kind. "all your dreams bundled together" means its a collection of games. The gift was a 15 in 1 game, containing foosball, airhockey, table tennis, basketball, bowling etc.


Question 2b, This is the clue to the location of the second question.
Posted by Hello
Answer to 2b - Start Higlighting here =>
This one is a bit complicated too. The first sign is an "ENTER" key, the second is some kind of dots, but "Dont make a mountain out of a mole hill" points to ants living in them. So, ENTER + ANTS = ENTRANCE and cloes to the shoe rack. So the gift was near the entrance :)

Chakarapongal: My Ethiri, made awesome chakarapongal for all of us. I was thinking its a ploy to kill me? I tried it, anyway. I usually dont like chakarapongal its too rich in ghee, gooey etc .., this one was really awesome, I had a lot of it. I am still alive :)


Monday, June 13, 2005

Book Tagging

Since Ethiri tagged me, here is the list.

Total books I own:
Ok, with 10 textbooks a year on an average, I studied for a quarter century of my life so,
10 textbooks/year x 25 years = 250 textbookss (figure out the trailing s, thats the geek)

250 other books so about 500?

Books I hate:
Self healing books, they are the worst, why would someone buy them ? :)

Favorite books:

First 2 books are just amazing

Last book(s) I bought:

Life of Pi by Yann Martel, I was patient enough to read 25 pages, I got my money back after that !

Rich Dad, Poor Dad , This is a good book, I am not sure I bought it :)

Last book I read:

The Automatic Millionaire, David Bach,This is a good book

Last Book I was Gifted:
1000 Places to see before you die, and I returned it :) I am not sure why this book is awesome, you can get all that information from the inet,

In my defense, Automatic Millionaire was also gifted.

Book that made 0 sense to me:
Life of Pi?

Now, is the time to tag someone, I tag

RS - This is the Koyal Singing (little bird chirping)

Mohan - Ha Ha, like I expect him to come up with a list.

Pradnya - You can use my comments section, until you get your own blogger id :)

Vasu - This guy is funny so he might have a good list. I am sure there will be a lot of Hindi books and shayri's

Monday, May 30, 2005

One day trip to The Great Smoky Mountains

Decent versions of the trip:
  1. D's version
  2. K's version

Indecent highlights of the trip (Ok some are not that indecent :) )
  1. P wanted to P: 10.30 AM, I get a request from P to take a gas exit. Unfortunately for him, I take the exit @ 12.30 PM. By that time all wanted to P :)
  2. Sitting Duck: D was trying to maneuver the tube around the river with the back of her hand lightly touching the water. You know what happened next, the tube headed straight for the banks and the trees.

  3. Successful rescue attempt: On the tubing trip R2 thought she was way ahead of everyone else, so she hung onto a tree branch just after a rapid, unfortunately for her the float wanted to carry on its downstream journey. The tree branch is not strong enough to hold her so she went into the water. R1 watched all this and came to rescue like a Knight in shining armor. She speeds up her tube to the bank breaks a tree branch in the water and tries giving it to R2. R2 holds onto the tree branch after a struggle, guess what happens next, the branch snaps! . R1 walks in a bit and gives the branch again, the branch snaps again. On the third try R2 was rescued to the comforts of dry land and the tube was a mile downstream :)

  4. P and D wanted everyone to trek: We started on the Big Creek Trail @ 7.30 in the evening, reached the mouse creek fall @ 8.45 PM. By the time we saw our car again, it was pitch dark. We saw a bearded man walking towards us while we were trying to get out and he was trying to get in??? We also saw some eyes in the bushes, some fire flies, P analyzed 3 different kinds of animal faeces. Which all of us stepped on :)

  5. In the nick of time: All of us thought it was going to become dark on the trail and we decided to head back without seeing the Mouse Creek Waterfall. S suggested we go on for 2 min on the trail to see if it is very near, and like a bull's eye, in 20 steps the waterfall was upon us. Thank You S. This delayed us further :)

  6. Nobody ate @ Shoney's: One thing, I have learnt, I am NEVER taking a desi gang to a soup, salad american place. I loaded 2 full plates, S and K ate some. But then, some other plates just had 3 onions and 2 cucumbers and a biscuit.

  7. Disclaimer: All the characters in this post are non-fictional and all pun, intended.